All Categories
Featured

Funding Future LTC Costs
Table of Contents
Successors can inherit a taxable financial investment portfolio with a "tidy slate" from a tax perspective. Such is not the case with variable annuities. Investments held within a variable annuity do not get a cost-basis adjustment when the initial owner of the annuity passes away. This means that any built up unrealized gains will be handed down to the annuity owner's heirs, together with the associated tax burden.
One substantial problem associated with variable annuities is the capacity for conflicts of interest that may exist on the part of annuity salespeople. Unlike a financial consultant, who has a fiduciary responsibility to make investment decisions that benefit the customer, an insurance coverage broker has no such fiduciary obligation. Annuity sales are highly rewarding for the insurance coverage professionals who offer them since of high upfront sales commissions.
The strong monetary incentive for insurance coverage salesmen to press variable annuity products raises questions relating to the suitability of such items for many investors to whom they are sold. Investors who are thinking about buying a variable annuity needs to fully think about these possible disputes of interest when figuring out whether or not such a product makes good sense in the context of his or her financial objectives.
Lots of variable annuity contracts contain language which positions a cap on the percentage of gain that can be experienced by particular sub-accounts. These caps prevent the annuity owner from completely taking part in a part of gains that could otherwise be enjoyed in years in which markets generate considerable returns. From an outsider's viewpoint, it would seem that financiers are trading a cap on investment returns for the previously mentioned guaranteed flooring on financial investment returns.
Rising Long-Term Care Premiums for 2026
As kept in mind above, give up charges can severely limit an annuity owner's ability to move possessions out of an annuity in the early years of the agreement. Further, while many variable annuities permit agreement owners to withdraw a specified quantity during the build-up phase, withdrawals beyond this quantity typically lead to a company-imposed charge.
Withdrawals made from a set rates of interest investment choice could likewise experience a "market price modification" or MVA. An MVA adjusts the worth of the withdrawal to show any changes in rate of interest from the time that the cash was purchased the fixed-rate option to the time that it was withdrawn.
Rather typically, even the salespeople who offer them do not totally understand how they work, therefore salespeople often victimize a purchaser's feelings to sell variable annuities instead of the merits and suitability of the items themselves. Our company believe that investors need to fully understand what they own and how much they are paying to own it.
The very same can not be stated for variable annuity assets held in fixed-rate financial investments. These properties lawfully belong to the insurance coverage company and would for that reason be at threat if the business were to stop working. Any assurances that the insurance coverage company has actually agreed to provide, such as an ensured minimum income benefit, would be in question in the event of a service failure.
Retirement Planning Fontana CAThe Importance of Comprehensive Care Strategies
Possible purchasers of variable annuities need to comprehend and think about the monetary condition of the issuing insurance coverage company before getting in into an annuity agreement. While the advantages and drawbacks of various types of annuities can be discussed, the real problem surrounding annuities is that of suitability. Simply put, the question is: who should own a variable annuity? This question can be tough to respond to, provided the myriad variations readily available in the variable annuity universe, however there are some basic guidelines that can assist financiers choose whether annuities should play a role in their monetary strategies.
of variable annuities, it would appear to us that the only investors who need to think about owning variable annuities would be those who: Remain in a high-income tax bracket and anticipate to be in a lower tax bracket in retirement; Have actually tired all other tax-deferral cars; Have little need for liquidity; Anticipate to have a significant remaining life expectancy; Are comfy giving up control of their capital to an insurance company; Are ready to accept complete or partial restrictions on the transfer of properties to their beneficiaries upon their demise; Have a really low tolerance for investment loss.
Retirement Planning Fontana CAIndividuals who do not satisfy these requirements would be much better served, in our evaluation, by putting their capital towards other kinds of financial investments that might potentially generate greater returns that are not dragged down by the high costs associated with variable annuities while also providing higher liquidity and potentially more optimal tax treatment.

Latest Posts
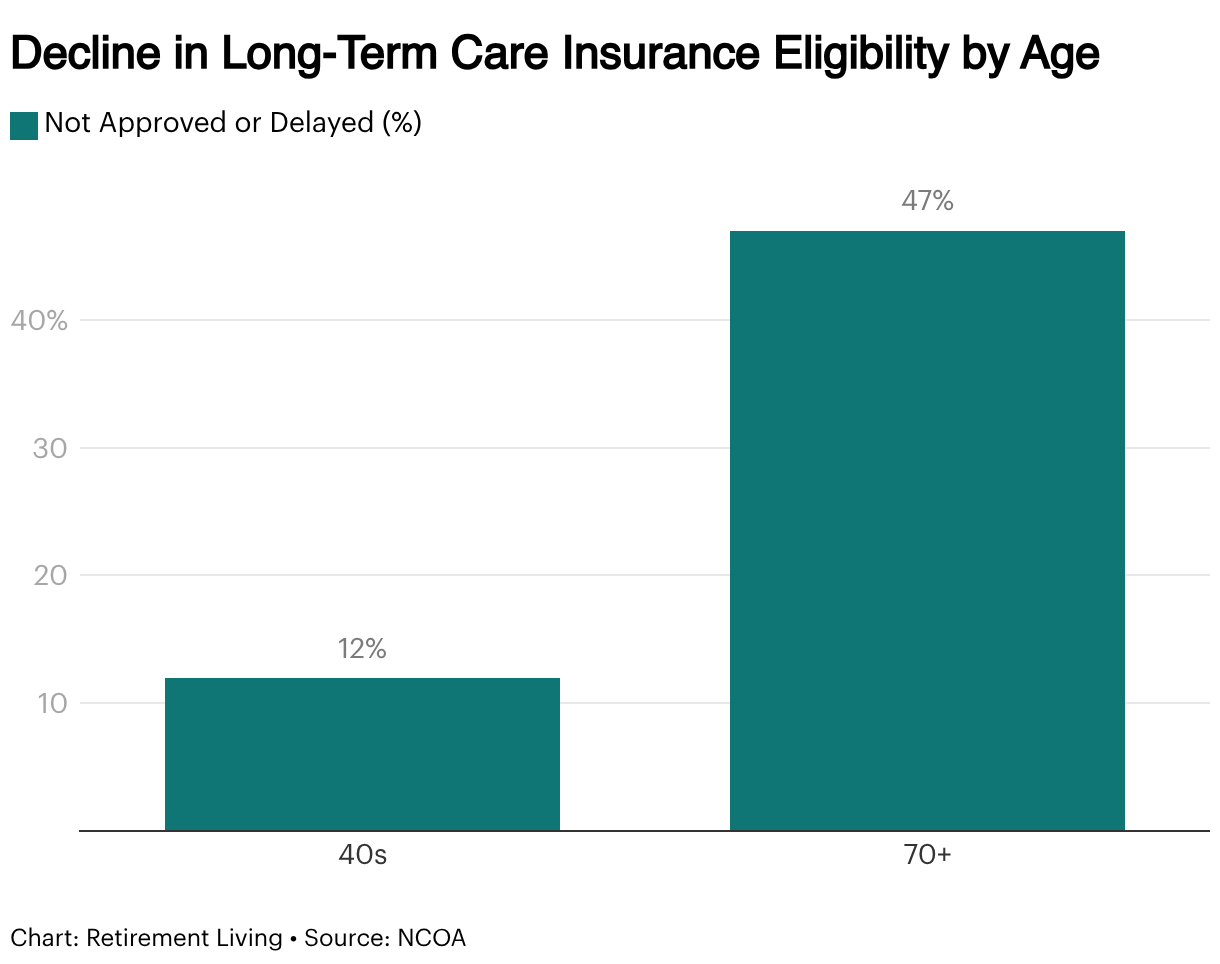
Navigating 2026 Long-Term Care Rates
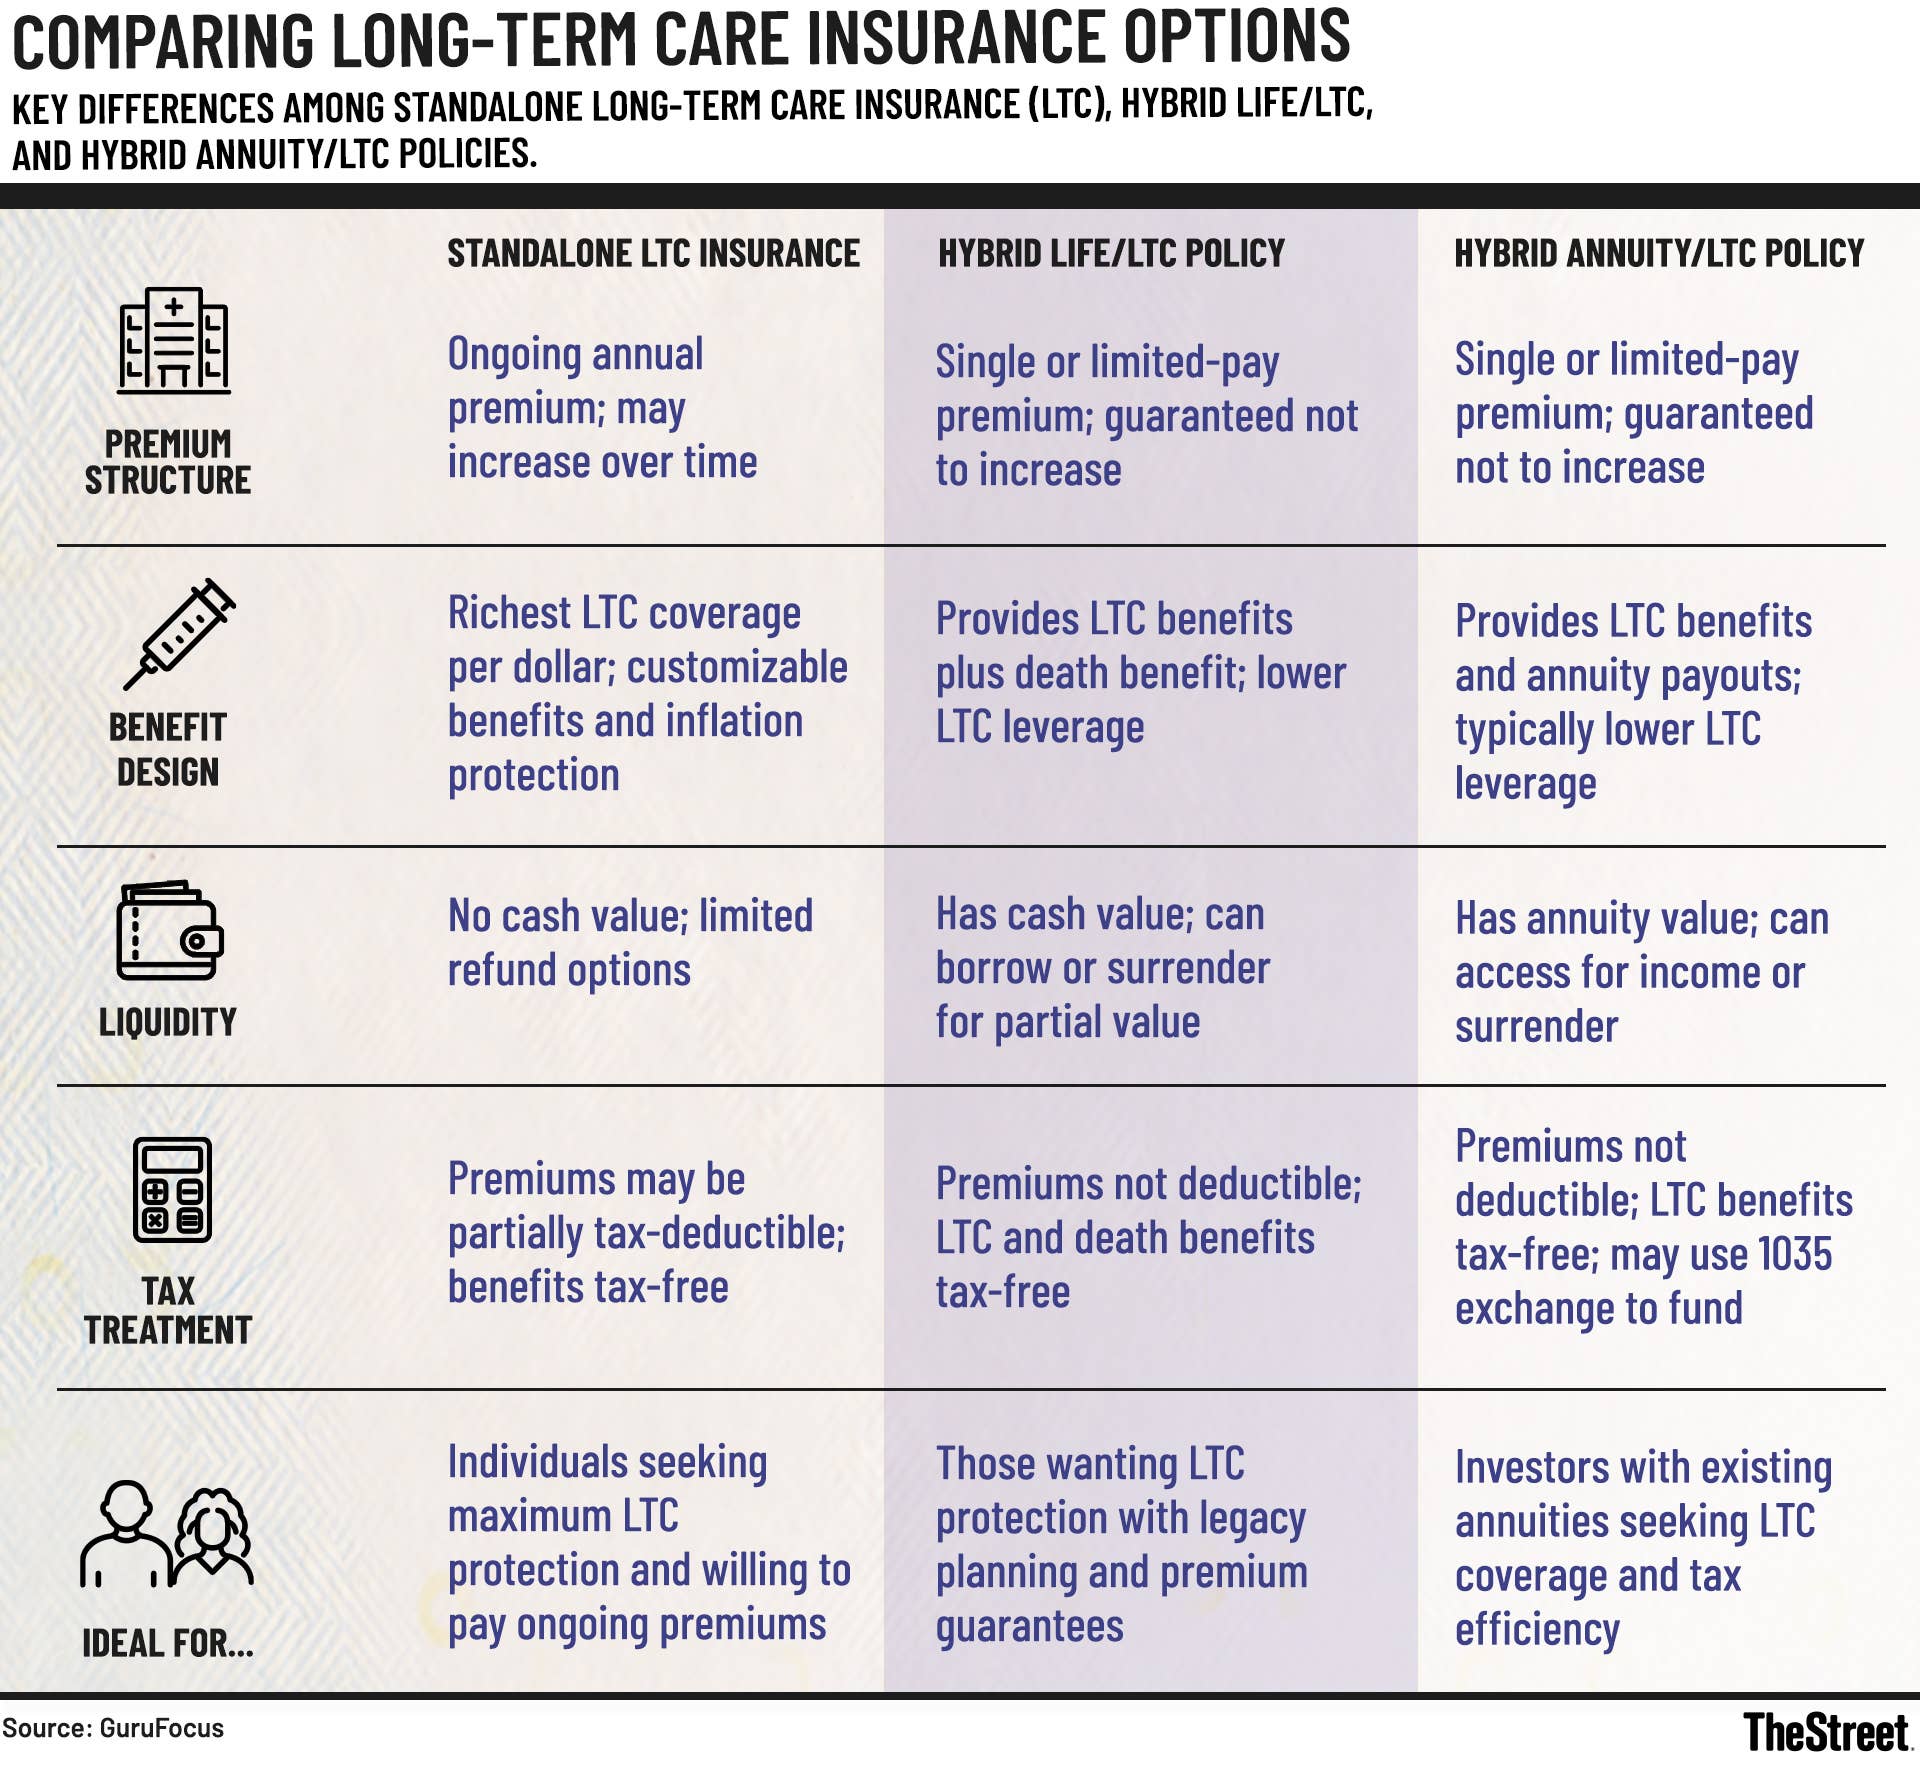
Comparing LTC Coverage Versus Medicare
Specialized Accident Insurance Policies