All Categories
Featured


Smart Ways to Secure Retirement Income
Table of Contents
When this happens, the insurance provider pays you dividends or interest, so the money in the policy grows as a sort of investment. When you do retire, you can begin taking cash out of the policy in the kind of a loan to yourself. You can keep taking money out of the policy as long as you want, whenever you need it, and it is just a loan to yourself. The only limitation on how much you can take out of the money balance is the quantity of the policy. When you ultimately pass away, your $1.5 million will pay off this.
$1.2 million loan and leave your successors about$ 300,000 in cash. The cash went into the policy, it was never taxed as it grew, and then you took it out without paying any taxes, because it was a just a loan. It appears too excellent to be true, however it is in fact all real and possible. This unique life insurance policy does not come low-cost.
Retirement Planning Anaheim CAInitially, the premiums are normally thousands and thousands of dollars every year. If you miss out on one of these premium payments, you may lose the insurance policy and possibly lose a few of the money you have actually developed in the policy. These sorts of policies need you to put in huge contributions of money each year for a certain variety of years. If you miss among those large contributions, then the benefits of the policy are typically lost. You have actually lost flexibility with the money. You are making a long-term, long-lasting choice that is tough to alter without losing cash in the future. Third, the interest and dividends paid on your money in the policy are typically low compared to what you might make in other places. Your money will earn below-market rates in the policy. The interest you earn might be fairly safe with an excellent insurance business, however you might generally earn more interest on your money without the requirement of locking the cash up with an insurer for a long time. The reason to get life insurance is to insure a life. For risk management. To secure individuals that you care about if you pass away all of a sudden. A life insurance policy can assist replace the earnings that your enjoyed ones are counting on you to supply.
Retirement Planning Anaheim CAAnd, a life insurance policy can pay off debt, your funeral expenses, and future education expenses for your child. After those things happen, you probably don't require life insurance. Due to the fact that with these risks it is possible to figure out about how many years your life requires to be guaranteed, it generally makes more sense to buy lower-cost term life insurance coverage for simply the variety of years (the term)that you need it.
Estimating 2026 LTC Expenses
The majority of people do not contribute the maximum amount the law permits them to contribute to their 401 (k) or individual retirement account retirement accounts. Yet, these are typically the first and finest choice for retirement savings for the majority of people. Until you contribute the legal maximum to these sorts of tax-advantaged, tax-deferred, or tax-free(Roth)pension, you ought to rule out any other prepare for retirement savings, such as using life insurance coverage or annuities for retirement. The big photo counts. How does this solution fit into your total monetary strategy? If you have a fee-only financial advisor and investment supervisor, they will help you put this new concept in the context of your total monetary life.
In this post I'm going to review Tax-free Retirement Preparation with Life Insurance. These are also known as Life Insurance Retirement Plans.
It is a crucial topic to keep in the rotation and come at it from multiple angles. I have 2 goals for this post. The very first is that I desire to show you how a life insurance policy can create 2 to 3 times the earnings from the very same amount in other kinds of savings. Let's start with this: 2 to 3 times what? Financial Advisors utilize The 4-Percent Guideline as a Rule-of-thumb for identifying the safe withdrawal rate from retirement savings.
You wish to take as much in earnings as you can, but you don't wish to run out of money while you are alive. Head out and do a search on"The 4% Guideline". If anything, the agreement nowadays is that 4%is expensive. You must understand that this indicates that an individual with$ 1 Million in a 401(k )can safely take $40,000 annually in circulations for as long as they live. If this individual is in a 25 %tax bracket, they will lose $10,000 to income taxes leaving them with just$30,000 of annual earnings for every $1 Million in retirement cost savings. Even even worse, if tax rates are greater, such as 40%, they will only net$24,000 after tax! If you look carefully at a properly-designed, maximum over-funded policy illustration, you will discover that the ratio of earnings to the prior year's cash worth is more like 8%. Have a look at this footnote for caveats and assumptions.What this implies is that somebody with $1 Million in cash value at retirement age might securely take $80,000 per year in TAX-FREE Earnings. It should be apparent that $80,000 is about 3 times the after-tax income of what our hypothetical$1 Million 401(k )can produce depending on the tax rate. Now I want to discuss to you HOW this is possible. This is what every expert gets wrong.
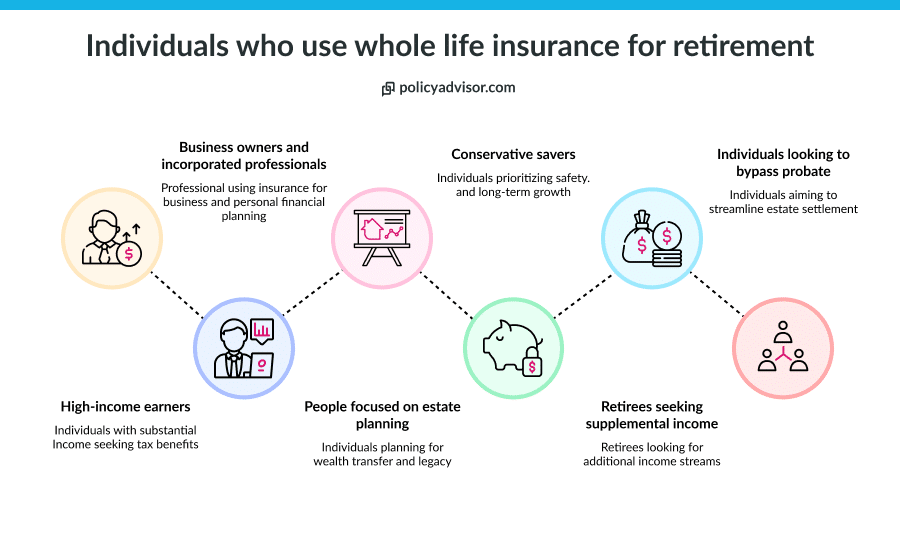
They simply do not comprehend how to transform cash value into"earnings ". The"so-called"experts just compare accumulation. If a tech mutual fund is growing at 10%each year, you are going to end up with a lot more money by the time you reach retirement age.
Economic Challenges of Increased Life Expectancy for Seniors
You desire to take as much in income as you can, but you don't desire to lack cash while you are alive. Go out and do a search on"The 4% Rule". The consensus nowadays is that 4%is too high. You need to understand that this implies that a person with$ 1 Million in a 401(k )can safely take $40,000 annually in distributions for as long as they live. So if this person remains in a 25 %tax bracket, they will lose $10,000 to income taxes leaving them with only$30,000 of yearly earnings for every single $1 Million in retirement savings. Even worse, if tax rates are greater, such as 40%, they will only net$24,000 after tax! If you look carefully at a properly-designed, optimal over-funded policy illustration, you will find that the ratio of income to the previous year's cash worth is more like 8%. Have a look at this footnote for cautions and assumptions.What this implies is that somebody with $1 Million in money worth at retirement age might safely take $80,000 per year in TAX-FREE Earnings. It should be obvious that $80,000 is about 3 times the after-tax earnings of what our hypothetical$1 Million 401(k )can generate depending upon the tax rate. Now I wish to explain to you HOW this is possible. This is what every expert gets wrong.
They just do not understand how to convert cash worth into"earnings ". The"so-called"professionals simply compare accumulation. If a tech mutual fund is growing at 10%per year, you are going to end up with a lot more money by the time you reach retirement age.

Latest Posts
Navigating 2026 Long-Term Care Rates
Comparing LTC Coverage Versus Medicare
Specialized Accident Insurance Policies